Bringing your mortgage current may resolve the default behind a foreclosure—but the amount, deadline, and conditions must be confirmed. Sending your usual monthly payment, requesting a quote, or saying funds are on the way does not itself stop a lawsuit or sale.
If you have funds available, review reinstatement promptly alongside the court case. The practical question is what must be paid, when it must arrive, and what will happen to the foreclosure afterward.
What is mortgage reinstatement?
Reinstatement generally means paying the past-due amounts and applicable charges needed to bring an existing mortgage current. You ordinarily resume payments under the existing loan terms.
Reinstatement
Catch up on the amounts required to restore the existing loan to current status.
Payoff
Pay the entire amount needed to satisfy the loan, rather than only the arrears.
Modification
Change agreed loan terms. A repayment plan instead spreads catch-up payments over time.
These options are not interchangeable. Freddie Mac’s reinstatement and repayment overview explains the basic distinction.
Can you reinstate a mortgage after foreclosure starts?
It may still be possible, but do not assume every loan has the same requirements or cutoff. The signed mortgage, applicable loan-program or investor requirements, any agreement with the servicer, and the court timeline all matter.
For example, Fannie Mae has servicing requirements for processing reinstatements during foreclosure. Those requirements should not be treated as rules for every mortgage.
If a judgment hearing or sale is scheduled, tell the attorney immediately. A possible option is useful only if its requirements can be completed in time. Our guide to stopping foreclosure in Florida explains why the stage of the case matters.
Check your mortgage’s “right to reinstate” paragraph
Look for a paragraph titled “Borrower’s Right to Reinstate After Acceleration,” or similar wording. Some standard residential mortgages set a contractual cutoff at the earliest of several events, including entry of a judgment enforcing the mortgage.
The Florida Supreme Court discussed that contract language in Bartram v. U.S. Bank. It is one reason to have the issue reviewed before a judgment hearing.
Your signed mortgage controls its contractual terms. Do not calculate a deadline from a generic form. Other applicable requirements or a separate agreement may affect the options; a contractual reinstatement cutoff does not mean every possible resolution ends at that point.
What should a mortgage reinstatement quote show?
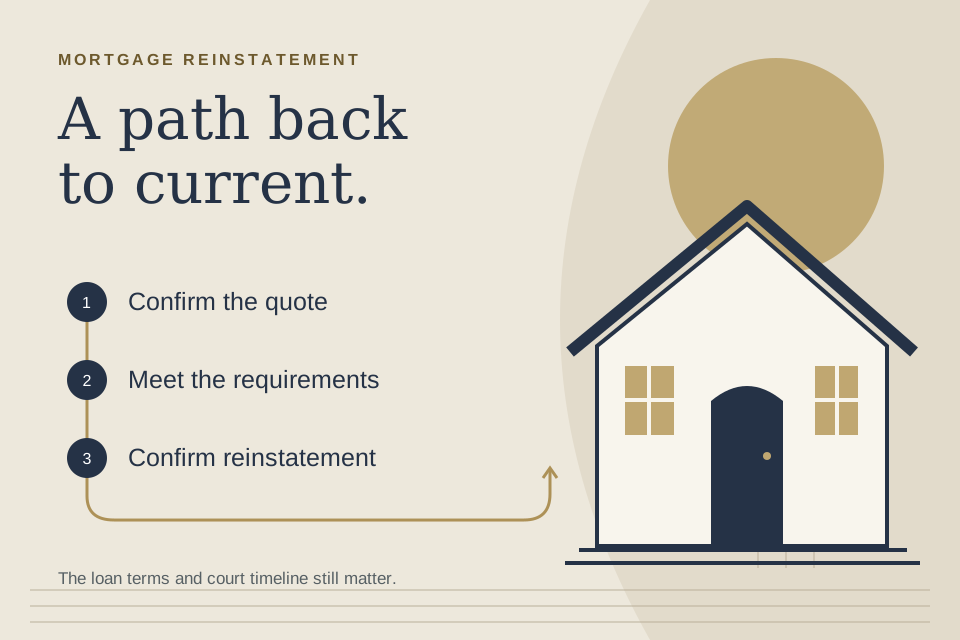
Ask for a current written quote rather than relying on an estimate from an old statement. Review:
- The missed payments included in the total.
- Late charges, legal expenses, and other fees.
- Payments already received and how they were credited.
- The date through which the quote is valid.
- Any additional payment or charge due before your funds arrive.
- The required payment method and delivery instructions.
- What will happen to the pending foreclosure when the requirements are met.
An older quote may no longer be sufficient. If the amount appears wrong, gather the quote, account history, and proof of the payments or charges you dispute.
Reinstatement is not the same as Florida’s right of redemption
Florida’s statutory right of redemption is a separate concept. Under §45.0315, after judgment redemption generally requires payment of the amount specified in the judgment, not simply the missed installments. Before judgment, the statute addresses tendering the performance due under the security agreement, including amounts due because of acceleration, plus qualifying foreclosure expenses.
The statutory cutoff is the later of the filing of the certificate of sale or the time specified in the judgment, order, or decree. That is not a universal deadline for reinstating a mortgage. Have the contract and the court record reviewed together.
Keep the payment and court case coordinated
Confirm who is handling the reinstatement, where the funds must go, and how the lender’s foreclosure attorney will be notified. Keep the quote, payment confirmation, correspondence, and written confirmation of reinstatement.
Separately check what happens to any hearing, judgment, or scheduled sale. A customer-service conversation does not itself change a court date. Our Florida foreclosure process guide explains the stages to keep track of.
What if you cannot afford the reinstatement amount?
The quote can still help clarify the problem. A repayment plan, a loan modification during foreclosure, or another resolution may deserve review. Consider whether you could maintain the payments after catching up—not just whether you can assemble a lump sum.
If keeping the property is not realistic, selling during foreclosure may be another option. Any sale must be coordinated with the payoff, title requirements, and court timeline.
Questions about catching up on payments
Can catching up on missed payments stop foreclosure?
It may resolve the default if you satisfy an applicable reinstatement right or agreement. Confirm the full amount, conditions, deadline, and how the case will be resolved. Paying overdue installments alone may not satisfy every requirement.
Will one mortgage payment stop foreclosure?
Do not assume it will. Ask how the payment will be accepted and applied, and obtain confirmation of its effect on the loan and case. A regular monthly payment may be far less than the amount required to reinstate.
Does requesting a reinstatement quote postpone a sale?
No automatic postponement should be assumed. The court case and sale can continue while you request or review a quote.
What should I bring to a consultation?
Bring the signed mortgage, current reinstatement quote, statements, payment records, and court papers—including any hearing or sale notice.
Find foreclosure information for your Florida county →
Sources and important context
- Freddie Mac: reinstatement and repayment
- Fannie Mae: reinstatements during foreclosure
- Florida Supreme Court: Bartram v. U.S. Bank
- Florida Statutes §45.0315
Published October 19, 2026. General educational information, not legal or tax advice. Coverage, deadlines, and available options depend on the loan documents and case history. Contacting the firm or sending a request to a servicer does not create an attorney-client relationship or itself suspend court proceedings. No outcome is guaranteed.